How to Compare International Transfer Costs: Fees, Exchange Rates, and the Recipient’s Amount
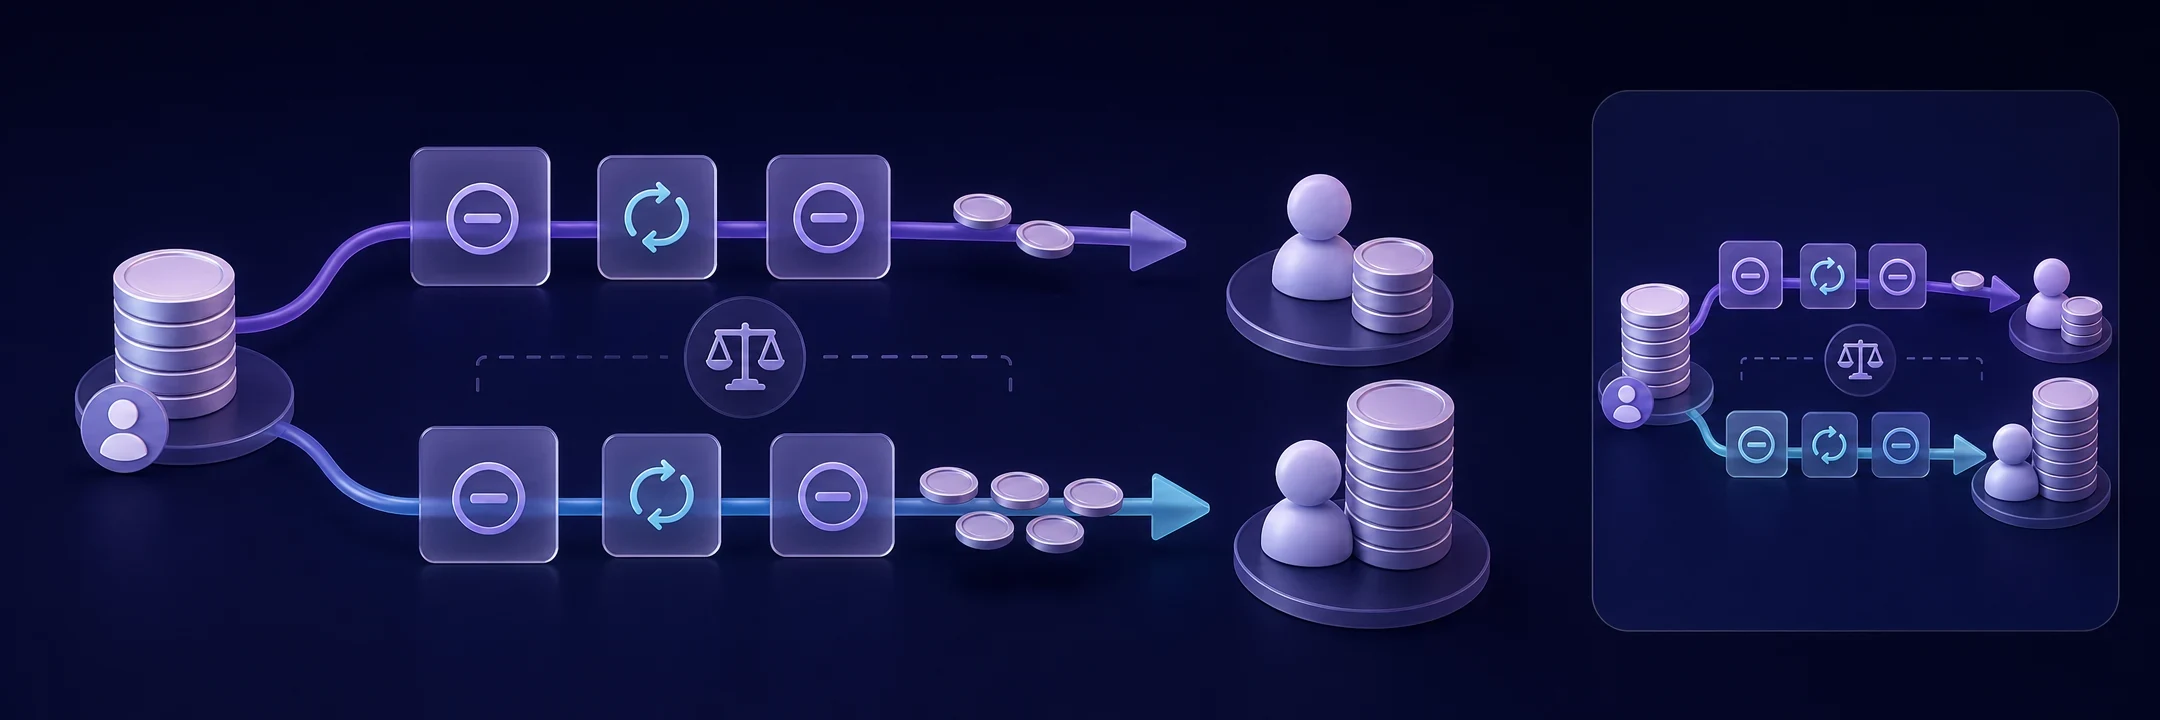
A small transfer fee does not necessarily mean a low-cost international transfer. The exchange rate and deductions along the payment route can matter just as much. The most useful comparison starts with two questions: how much will leave your account in total, and how much will the recipient actually receive?
This guide explains how to compare offers on equal terms, separate visible fees from exchange-rate costs, and spot uncertainty in a quote. The numerical example is entirely hypothetical and does not describe TopSend’s prices or conditions.
1. Set the same basis for comparison
Choose a fixed total spending budget in your payment currency. If your budget is 500 EUR, compare offers that debit 500 EUR in total, including any fees included in that debit. Entering 500 EUR as the transfer amount everywhere can produce different total charges when some providers add fees on top.
Keep these details identical across offers:
- The sending and receiving currencies, including the currency of the recipient’s account.
- The destination and the recipient’s payout method, such as a bank account or cash collection.
- Your payment method, such as a bank transfer or card.
- The approximate time you obtain the quotes.
Check any separate charges from your own bank or card issuer as well. If one payment method creates an extra charge outside the quote, include it in your budget. Otherwise, the offers do not represent the same total outlay.
2. Separate the cost components
The total economic cost can involve several elements. A provider’s prominently displayed fee may cover only one of them.
- Sending fee: a fixed amount, a percentage, or both. Establish whether it is added to your payment or deducted before conversion.
- Exchange-rate markup: the difference between the offered rate and a chosen market reference rate.
- Intermediary deductions: possible charges by institutions involved in passing the payment along.
- Receiving charges: possible fees or an additional currency conversion by the recipient’s bank.
Ask which charges are included, which are excluded, and which cannot be established in advance. An unknown deduction is not the same as a zero deduction. Avoid counting the same cost twice: if a receiving fee is already reflected in the quoted net amount, do not subtract it again.
3. Read the exchange rate in the right direction
For a straightforward comparison, express every rate as units of receiving currency per one unit of sending currency. With that convention, a higher rate gives the recipient more money for the same amount converted. A rate displayed in the opposite direction must first be inverted.
A market reference rate helps estimate the exchange-rate markup, but it is not necessarily a rate available to retail customers. Use the same reference source and a closely matched timestamp for all offers. Mixing a morning reference rate with an evening quote can make market movement look like a pricing difference.
Approximate markup (%) = (reference rate − offered rate) ÷ reference rate × 100.
This calculation isolates the rate difference. It does not include the sending fee or downstream deductions. For deciding between offers, the net recipient amount at the same total outlay remains the more practical measure.
4. Compare a hypothetical example
Suppose your total budget is 500 EUR, the recipient receives USD, and fees are deducted from that budget before conversion. Assume no separate payment-method charges and no intermediary or receiving-bank deductions. Every figure below is invented solely to demonstrate the calculation.
- Offer A: a 5 EUR fee and a rate of 1.0800 USD per EUR. The converted amount is 495 EUR. The recipient receives 495 × 1.0800 = 534.60 USD.
- Offer B: a 0 EUR fee and a rate of 1.0650 USD per EUR. The converted amount is 500 EUR. The recipient receives 500 × 1.0650 = 532.50 USD.
Offer A delivers 2.10 USD more despite its visible fee. Comparing only the fee would therefore produce the wrong ranking for this budget.
Now assume a hypothetical reference rate of 1.1000 USD per EUR. The reference value of the full budget is 550 USD. The shortfall is 15.40 USD for A and 17.50 USD for B. These differences combine the effect of the sending fee and the offered exchange rate; they are not additional charges.
If an unknown receiving fee could apply to either offer, those final amounts would no longer be assured. You would need the missing information before treating the comparison as definitive.
5. Distinguish an estimate from a guaranteed amount
A calculator preview may use an indicative rate. A later payment screen may show different figures because the amount, payment method, or market rate has changed. Compare quotes at the same stage of the process.
Check whether the terms guarantee the exchange rate, the recipient amount, or both. A fixed exchange rate alone does not establish that outside deductions are covered. Look for any conditions, such as a quote expiry or a requirement that funds arrive before a specified deadline.
Save the quote and its applicable conditions before confirming. If a provider cannot establish the recipient’s final net amount, record the known amount and the unresolved deductions separately. Do not treat a precise-looking number as a guarantee unless the terms support it.
6. Use a checklist before choosing
- Fix your total spending budget, including separately charged payment costs.
- Match currencies, destination, payment method, and payout method.
- Obtain quotes close together and note their validity conditions.
- Record the total debit, sending fee, exchange rate, and recipient amount.
- Check whether intermediary and receiving charges are included or still unknown.
- Compare the recipient’s net amounts and the certainty attached to them.
If the recipient needs a specific amount for an invoice or family expense, reverse the comparison: hold the required net receipt constant and compare the total cost to you. Use one basis consistently rather than switching between fixed-budget and fixed-receipt quotes.
7. Frequently asked questions
Is a zero-fee transfer always cheaper?
No. An exchange-rate markup or other charges can outweigh the saving on the sending fee. Compare the final recipient amount for the same total spending.
Can I compare offers in different receiving currencies?
Not directly. First establish the currency the recipient needs and account for any further conversion and its costs. Otherwise, you are comparing different outcomes.
What if intermediary fees are unknown?
Ask whether a net amount can be guaranteed and under what conditions. If uncertainty remains, label that quote as uncertain; do not assume the deductions will be zero.
How should I apply this when considering TopSend?
Open TopSend and review the information and terms available for your intended transfer. Apply the same checklist to any offer you receive, and clarify missing cost details before confirming.